USA: Florida inter-city operator Brightline has announced a financial restructuring of its parent holding company aimed at securing the future of its Miami – Orlando passenger service.
The private sector operator announced on September 25 that ‘certain entities associated with the company’ had entered into a Restructuring Support Agreement, which would ‘significantly deleverage Brightline’s balance sheet and greatly improve liquidity’.
Former Eurostar CEO Nicolas Petrovic, who joined the business in January as Chief Executive Officer at Brightline Train Development LLC, emphasised that ‘this is a financial restructuring that is not expected to impact operations. It will give Brightline the balance sheet to match the growth we’re already seeing across the business. Brightline continues to grow and the business is strong.’
Ridership and revenue increasing
Originally branded as All Aboard Florida, Brightline was established to develop inter-city passenger services between Orlando and southern Florida, identifying a business opportunity to connect the important tourist regions. It believed that the end-to-end journey time of around 3½ h would be competitive with the state’s overcrowded highway network.
The promoter raised substantial sums of debt to fund the reconstruction of the freight-oriented Florida East Coast Railway and the construction of a new line to Orlando International Airport. This was accompanied by transit-oriented property development initiatives around its principal stations.
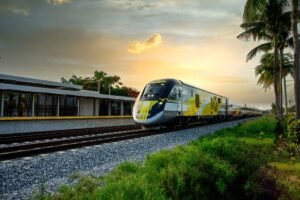
Having purchased a fleet of push-pull trainsets from Siemens Mobility, Brightline began operating between Miami and West Palm Beach in 2018, with the northern extension to Orlando opening in September 2023.
Ridership and revenue have been increasing steadily, with the company reporting a 14% year-on-year increase in revenue to August and a total patronage of 289 000 passengers in July. Responding to an 8% increase in local ridership between its five stations in southern Florida, Brightline revised its operations in October 2025 to offer a more frequent commuter service on the southern end of the line. However, this reportedly resulted in a drop in average revenue per passenger on the short-haul services while the yield on the longer-distance service remained steady.
Earlier this year, Brightline reported an operating loss of $127m on its train services in 2025, an improvement from the $153m for the previous year. However, the interest payments increased the total loss to $233m, impacting on its cash reserves, and ratings agency S&P Global withdrew its rating, effectively declaring the company a junk bond.

Financial restructuring
According to US media, Brightline’s various companies have amassed more than $5.5bn of debt, including $2bn of long-term debt on which it is scheduled to pay more than $2.5bn of interest over the coming decades. This includes at least four tranches of tax-exempt bonds issued as the construction phase progressed.
As part of the restructuring agreement, which is backed by financial stakeholders including Assured Guaranty Inc and an ad hoc group of Mutual Fund bondholders, ‘supporting stakeholders have committed to provide $490m of new long-term capital to Brightline Trains Florida LLC, consisting of $140m of additional senior debt and $350m of new junior debt.
‘The $2.2bn Brightline Trains Florida LLC Issue, Series 2024 (Tax-Exempt) Bonds and the existing bond insurance policy issued by Assured Guaranty will remain in place. In addition, the $985m Brightline Florida Passenger Rail Expansion Project, Series 2025B Bonds, the $925 million AAF Operations Holdings LLC Issue, Series 2024 (Tax-Exempt) Bonds and the $285.7 million AAF Operations Holdings LLC Issue, Series 2024A (Tax-Exempt) Bonds will remain outstanding, with no reduction in aggregate principal amounts.’
To implement the restructuring, some of Brightline’s ‘non-operating’ parent entities will file for Chapter 11 bankruptcy protection in New Jersey.
The operating business Brightline Trains Florida, Brightline Florida Holdings, which holds the rights to develop commuter service in Miami-Dade, Broward and Palm Beach counties, and AAF Operations Holdings, which indirectly holds the development rights for the planned Tampa extension, are not part of the Chapter 11 process.
Similarly, the bankruptcy filing does not affect the Brightline West project to connect Las Vegas with the Los Angeles metroplex. A Brightline West spokesman explained that the separate business was focused on completing its own financing arrangements so that project could also move forward.
Business as usual
Train operations in Florida are expected to continue unaffected by the restructuring. Brightline told local media that it would ‘continue to pursue growth initiatives’, including the development of an additional intermediate station at Cocoa Beach and the introduction of enhanced commuter services linking Miami, Fort Lauderdale and Palm Beach. Work on the proposed extension from Orlando to Tampa would also continue.
‘Brightline is a critical part of Florida’s transportation network that has changed the way people move around the state’, insisted Patrick Goddard, Chief Executive Officer of Brightline Florida. ‘Today’s agreement brings $490m in new long-term capital to Brightline from the stakeholders who know this business, and it comes at a time of real momentum. This transaction will be a catalyst for further growth in ridership and revenue. We are grateful to our creditors, advisors, vendors, teammates, and guests for their confidence throughout this process, and we look forward to the bright future ahead.’
Source: rg